
Sharia’h-compliant fintech Flooss says Shorooq is prepared to provide “much larger amounts” of capital as the Bahrain-based fintech prepares to expand into Saudi Arabia, the UAE and Oman following investment rounds this year.
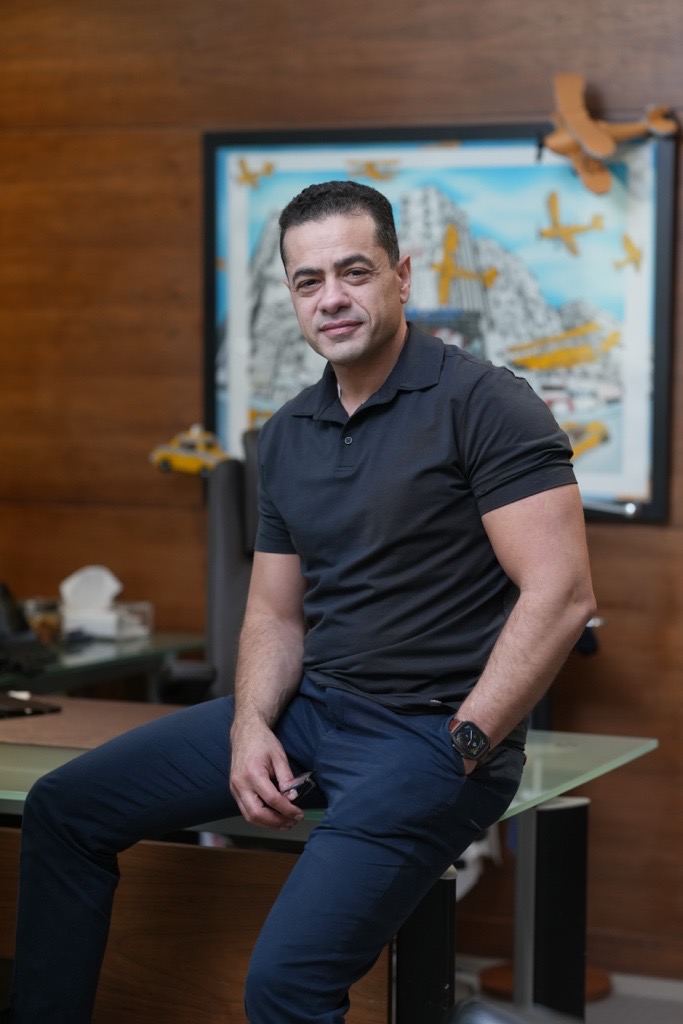
Speaking from Manama, Flooss’ CEO Fawaz Ghazal reiterated Shorooq’s confidence in the long-term fundamentals of the fintech as the firm scales-up operations in FY26-FY27 despite the ongoing Iran war.
The company received its first investment tranche from Shorooq in January totalling $22M, followed by a further $5M in April, according to Ghazal who said the second investment came despite heightened regional tensions.
“In the middle of the conflict, [Shorooq] invested another ticket in the middle of the conflict,” the CEO said. “And that’s a testimony of the power of our AI algorithm to detect and approve the right customers.”
Confidence inspires GCC expansion
The CEO said Shorooq’s confidence in Flooss’s lending performance could support larger funding commitments as the fintech seeks to scale beyond Bahrain, a relatively small market for consumer finance.
“Shorooq can provide much larger amounts because they see the performance,” the CEO said.
The comments point to the importance of funding access as Flooss prepares to enter additional Gulf markets and develop new sources of capital to support its lending operations.
Oman and Egypt possibilities
The company secured a licence in Saudi Arabia and is exploring expansion into the UAE, where the CEO said it had received an in-principle no-objection through a local partner.
Oman is also a target market, with Egypt among the company’s longer-term expansion ambitions.
Flooss expects to adapt its existing lending models for new markets rather than replicate its Bahrain operations unchanged.
“The models that we’re using here would need to be tweaked for KSA and UAE and they are in already,” the CEO said.
Credit lines
Alongside equity investment, Flooss is pursuing private debt to finance the expansion of its consumer lending business.
The company has signed an agreement with Bahrain investment bank SICO to test a $10M sukuk issuance, which is expected to launch by the end of FY26 after an earlier delay.
“We signed with them to do a test on $10M,” the CEO said. “We expect it by end of this year to be launched.”
Flooss is also in discussions with other private-debt providers, including multinational investors, regional family offices and other potential financing partners.
“Of course this is the way you need to scale any kind of financing company,” the CEO said. “You need to work with private debt… banks and others.”
Private debt strategy
He added that private debt was currently a key route for expanding the company’s lending capacity.
“Some of them are multinational regional family offices. They’re all interested in that market because this is a high yield type of product for them,” Ghazal said.
The CEO’s comments suggest that Flooss is seeking to combine investor funding with debt financing to support its next phase of growth.
However, the company has not disclosed the size or timing of any further Shurooq investment nor the proposed sukuk’s terms or investor commitments.
From BNPL to longer-term lending
Flooss is also developing its business beyond conventional buy now, pay later (BNPL) products, with embedded finance identified as its next major growth engine.
The company is building a platform to support lending through online and offline merchant checkout channels, with a focus on longer repayment periods and higher-value purchases.
“That’s the next big thing,” the CEO said. “Because I think we believe customers are not just bound to the BNPL in the 3 or 4 months type of model. They’re looking for 12 and 24 months models on a larger ticket item that can support them and empower them.”
The shift would broaden Flooss’s offering beyond short-term instalment payments, while creating additional lending opportunities through merchant partnerships.
The company’s ability to scale that model across the Gulf will depend on securing funding, adapting its credit assessment systems to local markets and maintaining lending performance as its customer base expands.
Stay Up to Date with the Latest Updates at Finance ME
Dubai Real Estate Reports 20% YoY Gain in 2025 Transactions
Defence Stocks Rally in EMEA and APAC with 50% U.S. Spending Boost
Qatar Financial Centre: H.E. Mansoor Rashid Al-Khater Appointed as New CEO