

Syria’s reopening is attracting Gulf capital, yet different GCC states are prioritising different pools of capital in their investment portfolios.
UAE companies are moving into property and logistics. Qatari capital is targeting agriculture, food production and banking. Saudi investment is extending into telecommunications and aviation.
The sectors are different as are the investors, ownership structures and commercial objectives. What links them is Syria’s potential to reconnect with the regional economy at a time when chokepoints are under geopolitical and commercial pressure.
That makes the current investment cycle different from a conventional reconstruction story. The opportunity is not simply to rebuild damaged infrastructure. It is to create the housing, production, finance, logistics and connectivity needed for an economy that can operate across borders again.
The scale of the gap is considerable. The World Bank estimates that Syria’s physical reconstruction needs total $216B, with almost one-third of the country’s pre-conflict gross capital stock damaged. Infrastructure accounted for $52B of identified physical damage, while residential buildings accounted for $33B. The estimated reconstruction bill is almost ten times Syria’s projected 2024 GDP.
Growth Rebounds
Yet the economy is beginning to move in the other direction.
The IMF expects double-digit growth in 2026 and continued strong growth in 2027, supported by recovering agriculture, higher hydrocarbon production, improved electricity provision, trade and services, as well as refugee returns and increased visitor numbers. Poverty remains widespread, while the banking system requires urgent rehabilitation.
The demographic pressure is also significant. IOM estimated Syria’s population at 27.43M in January 2026, including 6.08M internally displaced people. It recorded 1.94M IDP returnees since December 2024 and 1.12M arrivals from abroad.
The distinction between announced and deployed capital will therefore be critical. Syria has attracted large investment pledges and agreements, but individual projects still need financing, approvals and execution.
The more interesting question is what happens if the investments that do materialise begin to work together.
A new city needs businesses. Businesses need finance and connectivity. Agriculture needs processing and logistics. Ports need cargo. Trade routes need production on either end.
The Gulf’s involvement in Syria is therefore best understood as a series of different bets on the same emerging economy.
The City Bet
The largest headline investment so far is also one of the clearest examples of the urban thesis.
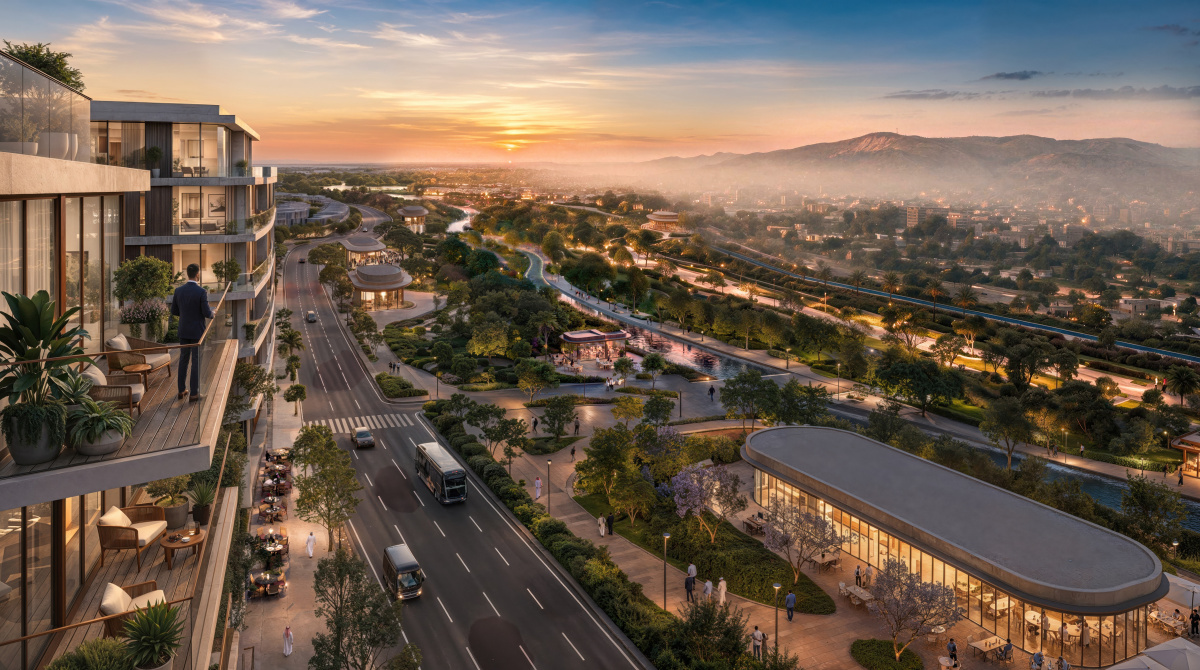
UAE-based Arada is partnering with the Syrian Sovereign Fund on New Damascus, a four-million-square-metre mixed-use development near the Mezzeh district. The project has an estimated gross development value of $7B.
The development is planned to include 11,000 homes, 500 hotel rooms, 1,000 serviced apartments, a 300-bed hospital, education facilities for 5,000 students, government service buildings, offices, retail and a 700,000-square-metre public park.
The numbers matter because the project is not being positioned as a single residential development.
Rosa Piro, Chief Investment Officer of Arada, says: “the site covers four million square metres near the Mezzeh district, approximately ten minutes from the centre of Damascus and twenty-five minutes from Damascus International Airport. The estimated gross development value of the site is $7B.”
Piro adds: “The project, known as New Damascus, comprises 11,000 homes across apartments, villas, townhouses and branded residences, alongside 500 hotel rooms, 1,000 serviced apartments, a 300-bed hospital, education facilities for 5,000 students, government service buildings, office space, retail and a dedicated public park of 700,000 square metres — close to one fifth of the total site.”
That makes New Damascus a bet on the return of a wider urban economy.
Housing is the starting point. The surrounding schools, healthcare, hotels, offices and retail are what give the development an economic base.
A Signal to Investors
Piro describes the project as a signal to other investors.
“It is one of the largest private mixed-use master plan developments announced in Syria, in one of the most sought-after locations around the capital. That signals a market moving toward integrated, long-horizon community development. The demonstration effect of a world-class development delivered by an internationally recognised developer in partnership with the Syrian Sovereign Fund is itself a powerful signal to other international investors that Syria is open, capable and ready for business.”
The investment also reflects Arada’s established model.
“Master-planned communities are what Arada builds, in every market we operate in. Aljada, a 2.2M square metre mixed-use mega community in Sharjah, is home to 20,000 residents today and will grow to around 70,000. Our three Masaar projects have shown how much demand a nature-led, lifestyle-focused community generates. Our UK and Australian operations have sharpened how we handle planning, governance and delivery in complex, regulated environments.”
But the company is not treating Damascus as another version of Sharjah.
“What changes is the context. Damascus is one of the oldest continuously inhabited cities in the world, with an architectural and cultural heritage that is entirely unique. Our master plan will be developed in close consultation with Syrian government authorities, local architects and urban planners, and cultural experts, so that New Damascus feels rooted in its context rather than imposed upon it. And it will be built with Syrian engineers, architects, contractors and professionals involved across every phase.”
That local element matters because the economic effect of a project of this scale will depend on how much activity it creates inside Syria.
Construction companies, engineers, architects, retailers, service providers and professional firms can all become part of the development ecosystem.
The same urban thesis is attracting other UAE developers. Mohamed Alabbar, founder of Emaar Properties, has discussed potential investments of up to $18B in Syria, including projects in Damascus and on the coast. The figure comprises projects worth between $5B and $7B on the coast and up to $11B in Damascus and surrounding areas. It remains a proposed investment pipeline rather than deployed capital.
Beyond a Single Asset
Arada’s own ambition is broader than New Damascus.
“I can speak to how Arada sees it. When Arada enters a market, we do not do single projects or trophy assets. Our ambition is to become one of the most significant developers in every country where we operate, as we are doing in London and Australia.”
Piro says the company sees underlying demand.
“We are in Syria to build a community people want to live in – the kind of place that changes what residents expect from a neighbourhood. The site supports that: four million square metres in a highly attractive location, just ten minutes from the centre. And the demand is real. Syria has a young, well-educated population of approximately 25 million with enormous pent-up demand for quality housing and community infrastructure.”
The bet is therefore on whether Damascus can support a larger formal economy around new housing and infrastructure.
The Maritime Bet
If Arada is betting on people and businesses returning to Damascus, DP World is betting on goods moving through Syria.
The Dubai-based logistics group has a 30-year concession to develop and operate Tartous port, with an investment programme of about $800M.
The programme includes infrastructure upgrades, cargo-handling equipment, digitalisation and operational improvements. In August, DP World said three new mobile harbour cranes had been delivered, with the equipment expected to increase the port’s cargo-handling capacity by approximately 40%.
Each crane is designed to handle roughly 2M tonnes of cargo annually.
That makes the project more than a conventional infrastructure rehabilitation exercise.
Tartous is one of Syria’s principal Mediterranean gateways. If cargo volumes increase, the economic impact extends beyond the port itself: freight operators, warehouses, manufacturers, importers, exporters and distributors all potentially benefit from more reliable logistics.
The commercial thesis is straightforward. Syria needs to import goods while domestic production is rebuilt. Over time, a stronger port can also support exports.
The challenge is whether there will be sufficient cargo to justify the investment.
That is where the other Gulf bets become relevant.
A larger agricultural sector generates bulk and processed goods. New industrial activity generates imports and exports. Urban development generates construction materials and consumer demand.
Port infrastructure only becomes economically transformative when there is an economy behind it.
Production
Qatar’s Baladna is taking a different position: rather than betting primarily on cities or logistics, it is betting on Syria’s productive capacity.
The company has announced a $3.3B agriculture and food-processing project covering 2,400 square kilometres in the Euphrates basin — equivalent to about 1.3 percent of Syria’s territory. The project is expected to cover wheat, cotton, textiles and dairy, with thousands of jobs expected to be created.
The scale reflects the importance of agriculture to the post-war economy.
Agriculture accounted for 43 percent of Syria’s GDP in 2024, compared with 21 percent in 2011, according to World Bank data cited by The National. But the rise in agriculture’s share is partly a consequence of the collapse of other parts of the economy; it should not be read simply as a doubling of agricultural productivity.
Baladna’s model therefore goes beyond land cultivation.
The project includes processing and dairy production, while the company has also discussed working with local farmers. That creates the possibility of moving from raw agricultural output towards higher-value domestic production.
It also creates potential links with other Gulf investments.
Processed food needs logistics. Agricultural businesses need finance. Large-scale farming needs electricity, equipment and telecommunications.
The project therefore provides another test of whether Gulf capital can create productive capacity rather than simply physical assets.
The Finance Bet
Banking may ultimately be one of the less visible but more important pieces of the recovery.
Estithmar Holding has completed the transfer of a 48.68 percent stake in Shahba Bank to Masaref Holding, a subsidiary of Estithmar Capital. The transaction received the necessary regulatory approvals and moved from agreement to execution in September.
Masaref says it intends to support proposals to strengthen the bank’s financial, operational and technological capabilities, including potential capital enhancement, branch expansion and new products and services for individuals, businesses and SMEs.
The need is clear.
The IMF says Syria’s banking system remains highly dysfunctional and that rehabilitation is urgent. It has called for assessments of banks’ financial health, new banking legislation, stronger supervision and improvements to the payments system. Reconnecting Syria to the international financial system also requires stronger anti-money laundering and counter-terrorist financing safeguards.
That makes banking infrastructure a prerequisite for much of the investment story.
A developer needs mortgages, corporate banking and payment systems. An agricultural producer needs working capital. Importers and exporters need trade finance. SMEs need credit.
Without those channels, physical investment can expand without creating a functioning private-sector economy around it.
The Connectivity Bet
Saudi Arabia’s investment is targeting another layer of the economy: the infrastructure that allows information, people and businesses to move.
stc’s Silklink project represents an investment of more than SAR 3B and includes more than 4,500 kilometres of fibre-optic networks, data centres and international submarine cable stations. The stated objective is to connect Syria regionally and internationally while supporting cloud services, data transmission and Internet of Things applications.
The number that matters is not only 4,500 kilometres of fibre. It is what that network enables.
Digital connectivity lowers the friction of running businesses across borders. It supports banking, logistics, e-commerce, government services and data-intensive industries.
PIF in Aviation
Saudi capital is also entering aviation.
flynas has agreed a 49 percent stake in a proposed Syrian low-cost carrier, with the Syrian Civil Aviation Authority holding 51 percent. The company is expected to begin operations in the fourth quarter of 2026, subject to licensing and operational requirements.
flynas currently operates 26 weekly flights between Saudi Arabia and Syria following the launch of direct Riyadh-Aleppo services in August.
The aviation opportunity is being reinforced by a separate $4bn Damascus International Airport development led by Qatar’s UCC Holding and an international consortium. The project is designed to raise airport capacity to around 31 million passengers a year across three terminals.
Again, the significance is cumulative.
More flights require passengers. More passengers require hotels, retail and services. More businesses require digital infrastructure and banking. More trade requires ports and roads.
Connectivity becomes valuable when the rest of the economy has something to connect.
The Corridor Bet
This is where the different investments begin to form a wider thesis.
Syria sits on the eastern Mediterranean, bordering Türkiye, Iraq, Jordan and Lebanon, with access to Mediterranean ports and established regional trade routes.
But the corridor should not be treated as an existing commercial reality waiting to be switched back on.
The infrastructure, security, financing and trade volumes required to create a meaningful regional logistics platform still must be built.
That is why the individual Gulf investments matter more than the headline total.
A port can handle cargo. A farm can produce food. A bank can finance companies. A telecom network can move data. An airline can connect cities. A development can provide housing and commercial space.
The economic value comes when those systems begin operating together.
From Announcements to Assets
Syria’s Gulf investment story is therefore less about a single reconstruction cheque than about the emergence of multiple forms of capital.
The scale of the opportunity explains the interest. The World Bank’s $216B reconstruction estimate is a reminder that the capital requirement is far larger than the Gulf projects announced so far.
But the gap between announcements and operating assets remains the central test.
Syria’s economy is recovering, but from a deeply damaged base. The IMF expects double-digit growth in 2026, while also warning that poverty remains widespread and that banking, fiscal institutions and financial infrastructure require further reform.
For investors, that means execution will matter as much as capital.
The next phase of Syria’s reopening will not be measured by the value of memoranda alone. It will be measured by homes delivered, cargo handled, farms producing, loans extended, flights operating and data moving.
If those assets begin to connect, the Gulf’s different investments could start to reinforce one another.
The city needs the bank. The bank needs the digital network. The farm needs the port. The port needs cargo. The airline needs passengers. Businesses need all of them.
That is the more consequential bet behind the Gulf’s return to Syria: not whether one project can succeed, but whether enough individual investments can become a functioning economy.
Stay Up to Date with the Latest Updates at Finance ME
How Al Masraf Is Building Islamic Trade Finance Corridors
EDGE’s Rodrigo Torres on Risk, Sovereignty and Defence Finance in a Multipolar World
ADNOC Distribution’s Ali Siddiqi: “Growth, Growth and Growth”