
Meet the leader behind the network that keeps capital flowing.
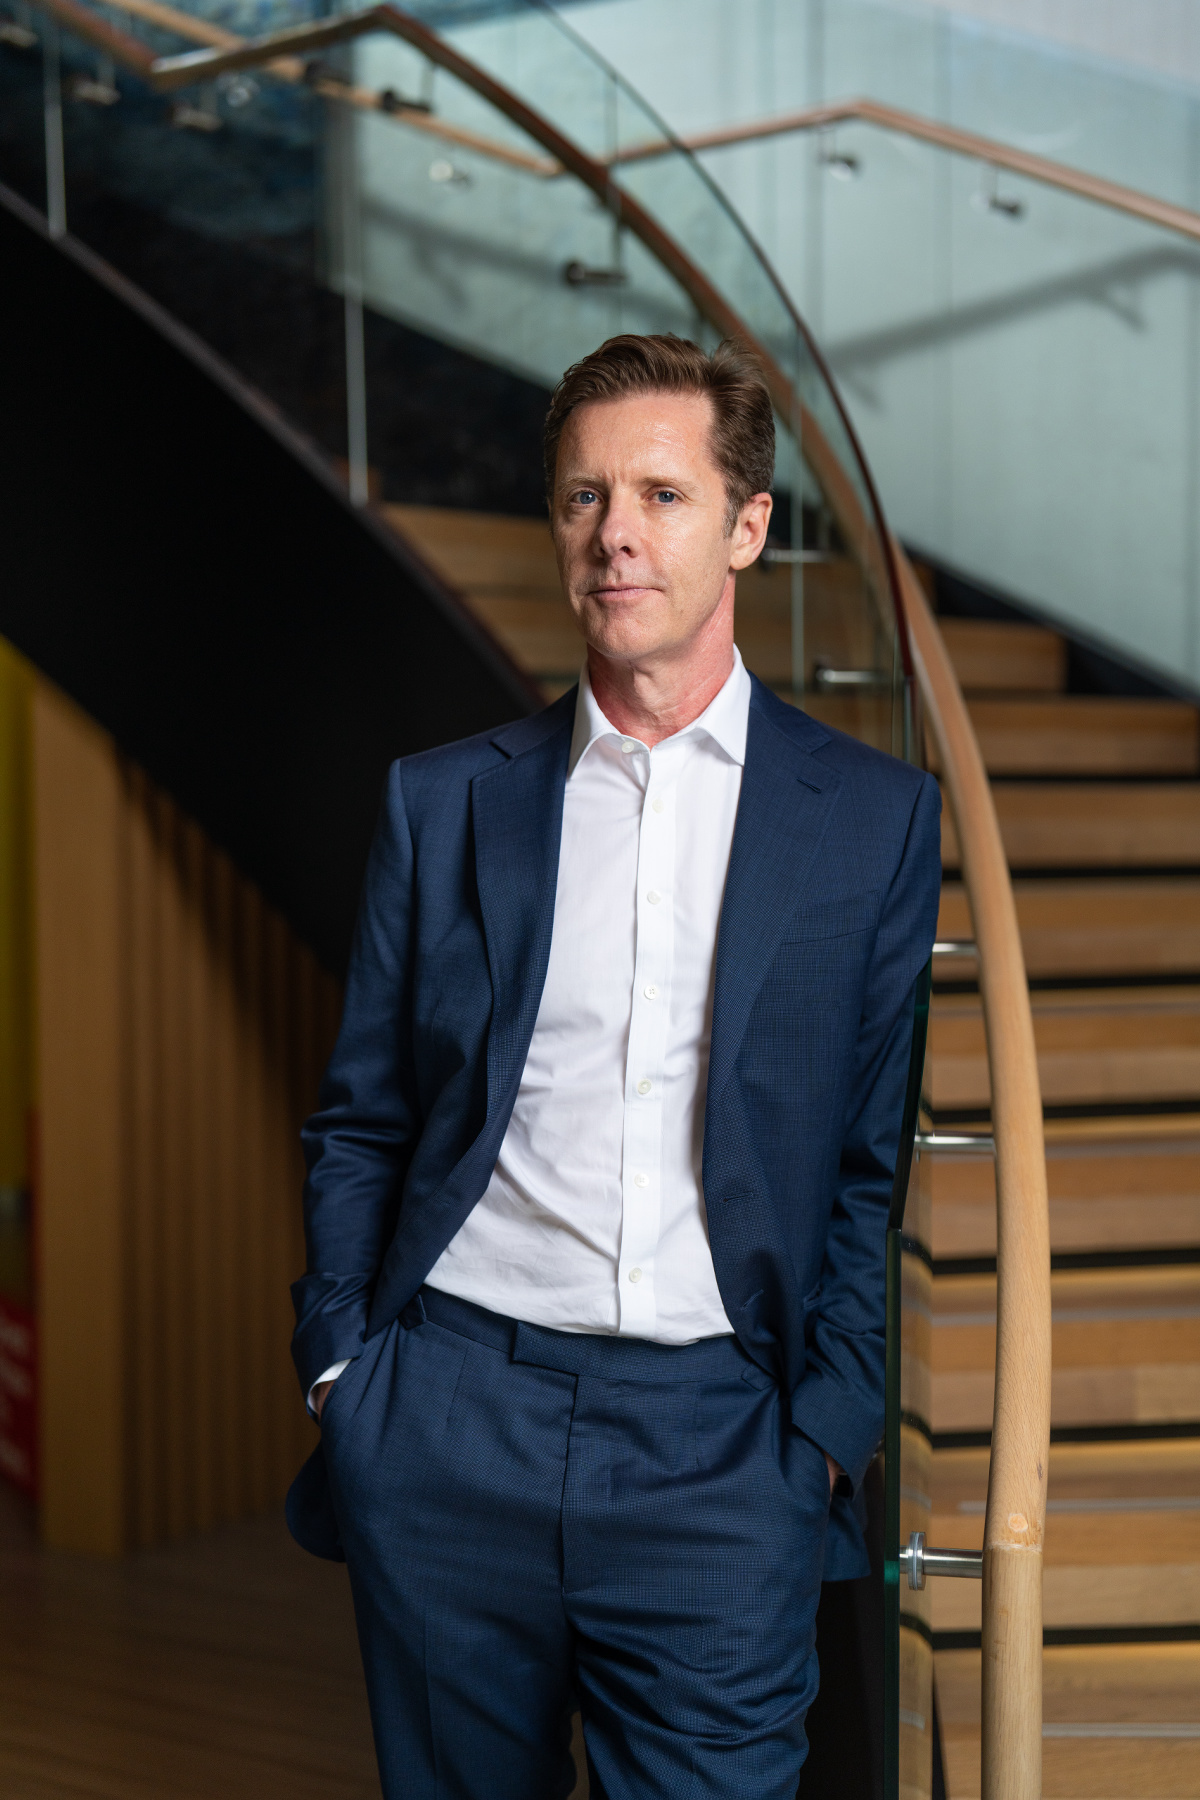
Finance Middle East spoke with Mark Elliott, Division President of East Arabia at Mastercard, for the cover of our June-July 2026 edition.
Elliott shares how Mastercard is strengthening national digital infrastructure, leveraging AI to combat cyber threats, and empowering SMEs to build a more resilient and connected economy.
How does Mastercard conceptualise the ecosystem given that its scope has evolved far beyond traditional payment rails?
Digital infrastructure has evolved from the transactional ‘plumbing’ of the global economy into a foundation of trust that empowers us to build a smarter, more secure, and more inclusive digital world. Today, it is the connective tissue enabling seamless, real-time interactions between consumers, businesses, and governments. This transformation expanded our focus from solely moving money to securely managing data, identity, and continuous innovation.
In times of uncertainty, robust digital infrastructure provides much-needed foundation for business continuity, stability, and resilience.
How is Mastercard supporting SMEs?
SMEs are the engine of economic growth and key drivers of innovation. They play a crucial role in fuelling progress by creating new job opportunities and reinvesting in their communities.
At Mastercard, we are committed to equipping every business with the digital tools, insights, technology services, cyber assessments, digital training, mentorship, and knowledge they need to thrive. We pledged to bring 50M micro, small, and medium enterprises (MSMEs) worldwide into the digital economy by the end of 2025. After exceeding our target by 15 million, we have set a new goal for ourselves – to connect and protect 500 million people and small businesses on their pathways to financial health by 2030.
The current climate, undeniably, is a catalyst for change. And SMEs are adapting with remarkable agility. At Mastercard, we support entrepreneurs and SMEs in scaling with digital solutions, payment acceptance, and knowledge-sharing. In response to the current situation, we have launched.
Built Small. Moving Strong, a regional SME resilience platform designed to empower small businesses to navigate uncertain times and unlock enduring growth. By working alongside our partners across the public and private sectors, we help ensure support reaches SMEs where it matters most. In addition, we are working with telcos and fintech companies to fast-track digital onboarding for SMEs so that they can accept online and contactless payments.
Together with governments and banks, we are enhancing access to capital for small businesses facing cash flow pressures and sharing data to inform their own SME support initiatives. As part of our long-term collaboration with First Abu Dhabi Bank (FAB), we have launched a three-tiered SME commercial cards suite that equips small businesses with smarter, more flexible tools to manage operating expenses, working capital, and day-to-day payments. We are also working with RAKBANK, which has committed approximately AED 2B in additional credit limits for new and existing customers.
Furthermore, we are collaborating with SME organisations to provide small businesses with near-real-time insights and targeted assistance to help them address shifting demand, adjust pricing and identify emerging growth corridors. We have recently co-hosted a webinar on navigating disruption with Female Fusion, the region’s largest network for women business leaders. Together with our wide ecosystem of partners, we are helping small businesses remain operational, connected, and protected so that they can continue to play their vital role in sustaining jobs, communities, and economies.
How are you driving public-private partnerships to specifically support and empower local SMEs?
Mastercard’s SME Confidence Index has revealed that many SMEs in the region are struggling to adapt to rapid digital transformation. They also must deal with rising costs, supply chain disruptions and shifts in consumer spending. At the same time, periods of uncertainty tend to increase exposure to fraud and financial risk, adding another layer of pressure. At Mastercard, we have launched QR code payments, Click to Pay, and Tap on Phone to enable widespread acceptance for SMEs.
These low-cost, scalable, and easy-to-use solutions allow freelancers, small e-commerce players, and tech-unsavvy merchants to generate links and accept payments without any additional technology integrations.
In the UAE, we are working with Geidea to provide SMEs with access to our payment gateway technology, offering advanced fraud prevention solutions and addressing the growing demand for recurring transactions and alternative payment methods, such as digital wallets. In Qatar, we have launched the ‘myPOS’ Tap on Phone service for micro and small businesses in collaboration with QNB. SME access to finance in the Arab world is the lowest globally – they account for only 7% of total bank lending.
At Mastercard, we are improving access to credit for SMEs through our collaborations with financial institutions and fintech partners. A prime example is our co-branded credit card with DP World and Emirates NBD that streamlines payments for shipments at the port for small businesses in the trade and logistics sector in Dubai. We have also joined forces with IFZA, one of the fastest-growing free zones in the UAE, and Global Tax Assistant to launch a fully digital, AI-driven business registration process.
Fintech companies play a key role in payment digitisation, which provides a robust economic foundation to address the wide range of challenges small businesses face. Connecting SMEs, which are often unserved or underserved by traditional financial institutions, to the digital economy greatly enhances ease of doing business. Digital solutions help small businesses pay and get paid, manage expenses, access funds, and obtain credit.
At Mastercard, we are committed to supporting fintech innovators in creating practical offerings that empower SMEs to succeed. We enable SMEs to benefit from innovative digital tools that help them streamline processes and reduce costs, such as the business subscription management platform powered by our technology partner Nuclei.
How has digital payment infrastructure held up across the GCC?
It has held up remarkably well.
According to data from the UAE Cyber Security Council (CSC), the country is now fending off around 800,000 cyberattacks every day – up from 200,000 before – and still succeeding. The CSC noted that attacks have intensified in frequency as well as sophistication.
This should serve as a call to organizations – both small businesses and enterprise level companies – for even greater awareness and active preparation. Because in the digital economy, cyber resilience is taking on ever-increasing importance every day.
The opportunism of bad actors during times of geopolitical uncertainty, just magnifies the reality. Our daily lives and our economies are built on digital foundations. And as we rely more on this infrastructure, we must also be diligent in protecting it. As adoption accelerates, stronger governance and deeper partnerships will be essential to ensure rapidly expanding digital systems continue to deliver meaningful outcomes.
This commitment to resilience is ultimately what sustains public confidence. While we may be navigating a complex new reality, the fundamental drivers of trust remain unchanged: secure payments, reliable infrastructure, and absolute transparency regarding the movement of capital. It is this intersection of security and stability that the GCC’s financial hubs are currently pursuing with laser-sharp focus.
How has the region built momentum around digital resilience?
GCC countries have long been recognised for their visionary leadership, robust public-private partnerships, and a collective drive to build a future-ready digital economy.
Driven by forward-thinking national strategies – such as We the UAE 2031, the UAE Centennial 2071, the Qatar National Vision 2030, and Qatar’s National Digital Agenda 2030 – the region has established a world-class digital infrastructure. This foundation continues to foster a thriving fintech ecosystem and the rapid adoption of secure, frictionless payment solutions that cater to a highly tech-savvy consumer base.
In an evolving digital financial services ecosystem, we are a technology enabler of choice that connects government entities, e-tailers, telcos, and fintech companies to fast-track the growth of the UAE’s digital economy. We provide technology solutions, platforms, and propositions that enable a superior digital experience for consumers and businesses.
A prime example of a successful public-private partnership is our collaboration with the Abu Dhabi Investment Office (ADIO) to launch the Abu Dhabi Digital Partnership Programme.
How does Mastercard help institutions drive future commerce and innovation?
The initiative aims to introduce innovative technologies to digitize government payment systems, support SME growth, and empower fintech companies. Our joint efforts are building on Abu Dhabi’s advanced financial infrastructure and enabling business ecosystem to drive impactful, sustainable economic outcomes.
We have also joined forces with the UAE’s Artificial Intelligence, Digital Economy and Remote Work Applications Office to establish the Center for Advanced AI and Cyber Technology in Dubai. We are working together to increase AI capabilities and readiness in the region.
The next frontier we are exploring with our partners is agentic commerce, which is changing the role of agentic AI in e-commerce from product search to personalized, autonomous shopping experiences, with AI agents proactively discovering and purchasing products for consumers.
Our latest milestone was the completion of the first agentic commerce transaction in the region, powered by Mastercard Agent Pay, in collaboration with Majid Al Futtaim last December. We are currently in discussions with more leading merchants in the region to expand use cases to grocery, F&B, fashion, and other segments.
How is consumer behaviour shaping Mastercard’s digital strategy?
According to our research, 2026 is shaping up to be the year of authentic intentionality, with people proactively seeking more thoughtful, meaningful ways of living.
Our proprietary data reveals that consumers are increasingly prioritising connection and spending time and money on what genuinely fulfills them – experiences with people who matter the most. Nearly 75% of our cardholders say they feel their best when pursuing their passions, including culinary exploration, artistic endeavors, and cultural immersion.
At Mastercard, we are moving beyond simply enabling transactions to actively curate the extraordinary. We are expanding our priceless platform and introducing premium offerings like the Mastercard Collection, ensuring our cardholders have unparalleled, frictionless access to the culinary, cultural, and artistic moments that bring them authentic joy.
How are you bringing your experience from Africa to your current position overseeing East Arabia?
Overseeing Africa for the last decade has been a masterclass in resilience, innovation, and human potential for me. The most important lesson I have brought with me is that innovation scales globally only when trust is built locally.
While foundational payment technologies can be seamlessly deployed across borders, consumer touchpoints must be tailored to the unique economic fabric of local communities. By supporting homegrown fintech ecosystems and aligning closely with national agendas, we can drive truly inclusive and sustainable growth.
In Africa, I have seen interoperability become the foundation of inclusion, and the same principle applies here across East Arabia.
Creating interoperability requires improving connectivity, building synergies, and designing alignment among very different entities. This connectivity can bring together multiple tech, data, regulatory, and financial ecosystems. Interoperability can also promote healthy competition and increase the economic viability of service offerings by reducing costs and unlocking economies of scale.
How is Mastercard using global intelligence to mitigate cyber crime?
We use global intelligence gained from protecting the billions of transactions we process on our network every year to equip our partners with advanced cybersecurity and fraud prevention tools.
For instance, our RiskRecon solution continuously monitors and acts on cyber risk from third parties, while Recorded Future, acquired by Mastercard in 2024 connects the dots across millions of sources to deliver the most comprehensive and unbiased threat intelligence in real time.
We are also using GenAI to supercharge consumer protection with Decision Intelligence Pro that has the potential to improve fraud detection by up to 300%.
Collaboration and shared insights are essential to boosting cyber resilience in today’s rapidly evolving threat landscape. At Mastercard, we are committed to working closely with our partners across the public and private sectors to strengthen trust in the digital economy.
We have teamed up with the CSC to build trust in the UAE’s digital ecosystem by sharing global best practices and supporting the development of forward-looking cybersecurity policies. This January, we published a joint report that provides an in-depth analysis of the country’s cyber threat landscape.
We also recently co-hosted the ‘Cyber Threat Intelligence’ webinar that examined the latest cyber risks and explored ways of driving operational resilience. In addition, we are collaborating with Dubai Police to raise public awareness about financial and economic crimes and promote the exchange of insights and expertise.
What does tokenisation mean for everyday consumers?
Tokenisation replaces your 16-digit card number with a secure, unique digital identifier; a token. Because your actual card details are never exposed, if intercepted, the data is just a meaningless string of characters.
It brings the security and simplicity of a physical contactless tap to the online world. For shoppers, this means a fast, frictionless, and safe checkout, while for merchants, it translates to reduced cart abandonment and meaningful financial benefits.
According to our joint report with Checkout.com, tokenised transactions across the payment service provider’s merchant portfolio in the Middle East and North Africa recorded 12.4 ppt higher approval rates than regular card transactions last year.
Globally, Checkout.com’s merchants saw a 49% reduction in fraud-related chargebacks and a 7.2% boost in gross sales revenue thanks to tokenization. These are tangible results that help businesses thrive.
According to Checkout.com’s data, tokenization adoption across MENA grew by almost 345% year-on-year, making it one of the fastest growing regions in the world for tokenisation.
Today, Mastercard has more tokens enabled for digital payments than physical cards in circulation, processing over a billion tokenized transactions globally each week.
Building on this momentum, our vision is to phase out manual card entry entirely, achieving 100% tokenisation for e-commerce transactions on our network by 2030. By combining tokenization with seamless biometric authentication, we are ensuring that the future of online commerce is universally safe, simple, and completely frictionless.
How is Mastercard leveraging global expertise and best practises to equip customers with added knowledge and skills?
Over three decades ago, we established Mastercard Academy that provides payment professionals with limitless learning at their fingertips, delivered by more than 150 top-tier experts.
To date, Mastercard Academy has hosted live training sessions for over 42,000 attendees, conducted more than 7,000 trainings, and achieved 90% customer satisfaction. We continuously update our training to reflect the latest trends in this ever-evolving industry.
Last year, we brought Mastercard Academy to the region with the launch of the Mastercard Eastern Europe, Middle East and Africa (EEMEA) Academy Hub in Doha, creating a learning and innovation ecosystem powered by Mastercard and world-class business schools.
We aim to equip financial industry professionals from across the region with highly sought-after knowledge and skills that will enable them to take their careers to the next level. This way, we contribute to fostering a highly qualified workforce that can assume an active role in shaping a thriving digital ecosystem.
The Hub supports the objective of the Qatar National Vision 2030 to develop a dynamic and sustainable knowledge-based economy, built on innovation, diversification, and resilience.
We have signed up HEC Paris, the world’s top-ranked business school for executive education, as the official academic collaborator for our executive education programs under the Hub, starting with the Mastercard Fellowship Program in Artificial Intelligence.
Looking ahead, what are the key emerging risks that leaders should be focussed on to ensure the financial system remains resilient?
The region is witnessing such a disruption right now, and it has proven that it is very well-prepared.
As economies become more connected, trust becomes essential. The rapid expansion of digital payments and services has unlocked opportunity but also heightened risk. In this environment, resilience depends on secure infrastructure, real-time intelligence, and strong collaboration to ensure that commerce remains seamless and protected.
For more than four decades, Mastercard has been working alongside the region’s governments, banks, fintechs, and merchants to help build a commerce ecosystem designed to withstand disruption.
The region has consistently been a launchpad for innovation – from scaling contactless payments at a national level, to advancing real-time payment capabilities and pioneering secure digital solutions that enhance trust. In many ways, the region has not just adopted the future of commerce, it has helped define it.
There is no doubt that 2026 represents a new reality for the Middle East.
But the region’s story is not being defined by disruption. It is being defined by something far more powerful: a commerce ecosystem built to keep moving – no matter the circumstances.
About Mark Elliott
Mark Elliott is the Division President for East Arabia, leading the expansion of payments, the extension of services and the adoption of new networks across the region. He is responsible for the overall performance, strategic direction, and brand development of the East Arabia Division. Prior to his current role, Mark served as Division President for Africa, where he played a pivotal role in advancing digitisation, strengthening commercial performance, and supporting growth across a diverse set of markets.
Stay Up to Date with the Latest Updates at Finance ME
How Al Masraf Is Building Islamic Trade Finance Corridors
EDGE’s Rodrigo Torres on Risk, Sovereignty and Defence Finance in a Multipolar World
Presight AI to Expand Kazakhstan AI Hub, Open Azerbaijan Office