

As Khazna expands into Saudi Arabia, the fintech is entering a market where financial inclusion is increasingly moving beyond basic access to the relevance, accessibility and personalisation of financial products.
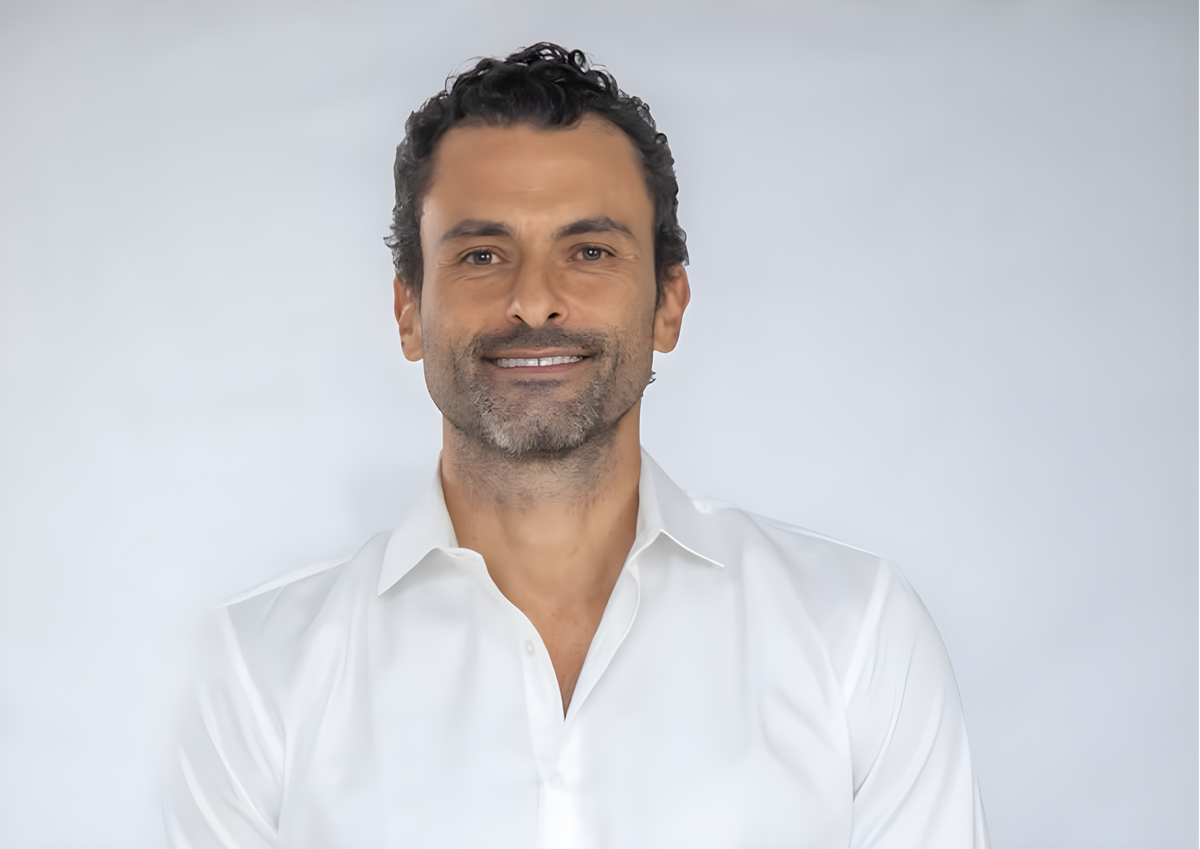
I spoke with Khazna’s Co-Founder and Group CEO Omar Saleh about the company’s Saudi expansion, what its experience serving underserved consumers in Egypt has taught it and how that blueprint will evolve in the Kingdom.
We also discussed Khazna’s approach to responsible growth, AI-led underwriting, its ambitions to build a broader financial platform and what the next five years could look like for the business across MENA.
Khazna has expanded into Saudi Arabia as the Kingdom accelerates the digitisation of financial services. What gap in the Saudi market are you targeting and why now?
Our view on the Saudi financial sector is very positive. It’s one of the region’s most promising markets, backed by clear direction under Vision 2030 and strong momentum across banks and fintechs, with SAMA striking the right balance between innovation and stability.
The market is also maturing beyond payments into credit, savings, insurance, and wealth, opening real opportunities to serve broader customer needs, and for us, the clearest opportunity is the underbanked segment: digitally active customers still underserved by the right products.
As competition grows, success will come from solving real problems and scaling sustainably, not just launching another app. We see Saudi Arabia becoming a leading fintech hub in the region, and we intend to be part of that growth.
What can Khazna’s experience in Egypt teach you about building financial products for underserved consumers in Saudi Arabia and what needs to be different?
Egypt taught us something specific: the problem was never appetite or awareness, it was that no one had built a product for this segment at all. Gig workers, low-income employees, even people with payroll running through a bank, were still locked out of banking facilities because banks classified them as high risk. They weren’t unbanked so much as unserved. Khazna’s Salary Advance product filled that exact gap, a B2B2C model where we partner directly with employers to reach their workforce, and we extended that same model through a strategic partnership with Egypt Post to reach their pensioners.
That’s not a niche use case; that’s a large share of the population with no formal product built for how they actually earn and spend.
What we take from Egypt into Saudi isn’t the product itself; it’s the tech, product, and operations expertise we built solving that problem at scale. How to underwrite responsibly for a segment banks won’t touch. How to build distribution through institutional partnerships rather than trying to acquire consumers cold. How to run compliant, high-volume salary-linked lending operations.
Saudi will test that expertise differently, because the gap isn’t the same shape. KSA has far higher banking penetration.
The gap is more about relevance and fit: products that speak to a younger, digitally fluent population with different cultural expectations around credit, and a regulatory environment that’s more prescriptive from day one. So we’re not exporting the Egypt product, we’re building this from the ground up: a new brand identity grounded in real research, not assumption, and a licensing path suited to how Saudi regulators want fintech to operate, not how we operated in Cairo.
The question we’re asking on the ground here is the same one that worked in Egypt: who is genuinely underserved, and what does a product built around their actual financial reality look like? The answer will differ. The rigour we bring to finding it is what Egypt taught us.
As Khazna scales across MENA, how are you balancing rapid customer growth with profitability, credit quality and capital efficiency?
Growth without credit discipline isn’t growth, it’s just deferred loss. So the way we think about scaling across MENA is: distribution and underwriting have to move together, never one ahead of the other.
Our B2B2C model is actually our biggest lever for capital efficiency here. Because we reach customers through their employer or through an institutional partner like Egypt Post, we already know something about them before we underwrite them, a verified income source, a stable relationship, a channel we can collect through. That’s structurally lower risk than acquiring a customer cold and hoping the data catches up later. It means we can grow the top of the funnel without loosening what we’d accept at the bottom.
The second piece is that we don’t treat credit quality as a risk function bolted onto a growth function, it’s built into the product from day one, market by market. In Egypt, that discipline came from years of underwriting a segment banks wouldn’t touch and having to get it right, because there was no legacy playbook to fall back on.
As we move into Saudi and other markets, we’re not relaxing that standard to hit expansion targets faster, we’re re-earning it against each market’s own regulatory and consumer reality, the same way we did with our licensing approach in KSA.
So the honest answer is: we don’t see growth and profitability as a trade-off to be managed, we see disciplined underwriting as the thing that makes the growth durable in the first place.
A customer we get wrong isn’t growth. A customer we get right, at scale, is the entire business model.
Do you see Khazna ultimately becoming a broader financial platform, rather than focusing on a single product or segment?
Yes, but not by chasing breadth for its own sake. The way we see it, Salary Advance was never the end point, it was the entry point. It’s how we earned the right to serve a segment no one else was underwriting properly, and in doing so we built the infrastructure that any broader platform actually needs: verified income data, employer and institutional distribution, and a track record of responsible lending at scale.
You can see that playing out in Egypt already. We started with Salary Advance, and from there came the Khazna Card, bill payment, our strategic partnerships with Egypt Post, and Social Housing and Mortgage Finance Fund (SHMFF) each one didn’t come from a roadmap sitting in a boardroom, it came from insights our own users gave us as we grew.
By closely monitoring and analyzing their data and behavior with the first product, we understood what else they needed from us. That’s the model: earn the trust with one thing done right, then let the data tell you where to go next.
That’s exactly the discipline we’re carrying into Saudi. We’re not walking in with the full Egypt product suite and assuming it transfers; we’re starting with the same principle, earn trust with the first thing done right, then let the data from how KSA users actually behave tell us where the platform needs to go from there. So the ambition is absolutely a broader financial platform but built the same way in every market we enter, sequentially and grounded in what the segment actually asks of us, not a land grab of features decided from the top down.
We’d rather be the platform people trust because we listened our way there, than one that tried to be everything before it proved it could be one thing well.
How is AI changing the way Khazna approaches credit assessment, underwriting and customer service and where does human judgement remain essential?
AI gives us powerful tools to sharpen decision-making, speed up underwriting, and surface insights that traditional models miss, all while keeping fundamental financial discipline intact.
Our support team is our largest team at Khazna, and that’s deliberate, they’re trained for customer centricity, not just resolution speed. On the credit side, we hold AI to the same discipline: before any AI-driven outcome goes into full deployment, it has to closely align with our existing rule-based model, so we’re never letting a new system loose on real customers’ credit lives until it’s proven to make the same calls, or better ones, than the discipline we already trust.
And that scrutiny doesn’t stop at deployment; we run continuous quality audits specifically on rejections, going back to evaluate whether they were actually accurate, because that feedback loop is what keeps the model honest over time, not a one-off validation we run once and move on from.
That said, human judgment is irreplaceable when it comes to setting credit policies, managing risk frameworks, and evaluating edge cases where data doesn’t tell the whole story. It’s not AI versus humans; AI helps us process signals at scale, and human judgment ensures we apply those insights responsibly.
What role do banks, telecom companies and government-backed digital infrastructure need to play alongside fintechs to accelerate financial inclusion across the region?
Here’s the honest truth, financial inclusion isn’t something fintechs can solve alone, no matter how good the product is. It takes the full ecosystem working together from banks, telcos, government infrastructure and fintechs and each player has a role only they can play as each solves a different part of the problem.
Banks bring the funding and the core financial infrastructure that everything else sits on top of. Telcos bring distribution and reach, and that matters enormously for customers who live outside traditional banking channels entirely. Government and digital infrastructure make onboarding and underwriting far more efficient, which sounds technical, but in practice it’s what determines whether someone gets approved in minutes or gives up after days of paperwork. And fintechs like Khazna bring the product and the customer experience which supports in moving faster and focusing specifically on underserved segments.
The real value comes from connecting these pieces: better data leads to better underwriting, better infrastructure lowers the cost to serve, and better distribution means wider access.
How has the investor conversation around fintech changed since the era of ‘growth at all costs’, and what are investors demanding from Khazna today?
A few years ago, market conversations were dominated by user acquisition and GMV. Now, investors prioritise high-quality growth, business health metrics, and a clear path to profitability. That shift aligns well with how we operate. We’ve always prioritised risk management and portfolio quality alongside growth, maintaining a strong focus on customer retention, repeat usage, and long-term relationships.
Looking five years ahead, what would success look like for Khazna regarding scale, profitability and its impact on financial inclusion across MENA?
Five years from now, success means Khazna becoming the primary financial partner for millions of customers.
In Egypt, that means evolving into a full digital bank. In KSA, it means building a large-scale financial services business around credit and adjacent products. And beyond that, it means expanding that model into selected regional markets.
At the core of this is a deeper customer relationship; a platform where a customer can access credit, savings, payments, and broader banking products all in one place, built around how people actually earn, spend, and manage their money, especially customers who have historically been underserved by traditional financial services.
Success also means being large and profitable at scale; millions of customers, strong economics, and diversified funding, with scale itself strengthening the model over time.
But the bigger ambition sits beyond the numbers. It’s not just about adding more customers to an app, it’s about financial inclusion by bringing millions of people into the formal financial services ecosystem, and giving them access to products that were previously difficult, or impossible, for them to get.
Stay Up to Date with the Latest Updates at Finance ME
EDGE’s Rodrigo Torres on Risk, Sovereignty and Defence Finance in a Multipolar World
ADNOC Distribution’s Ali Siddiqi: “Growth, Growth and Growth”